

Week of Friday October 16, 2026
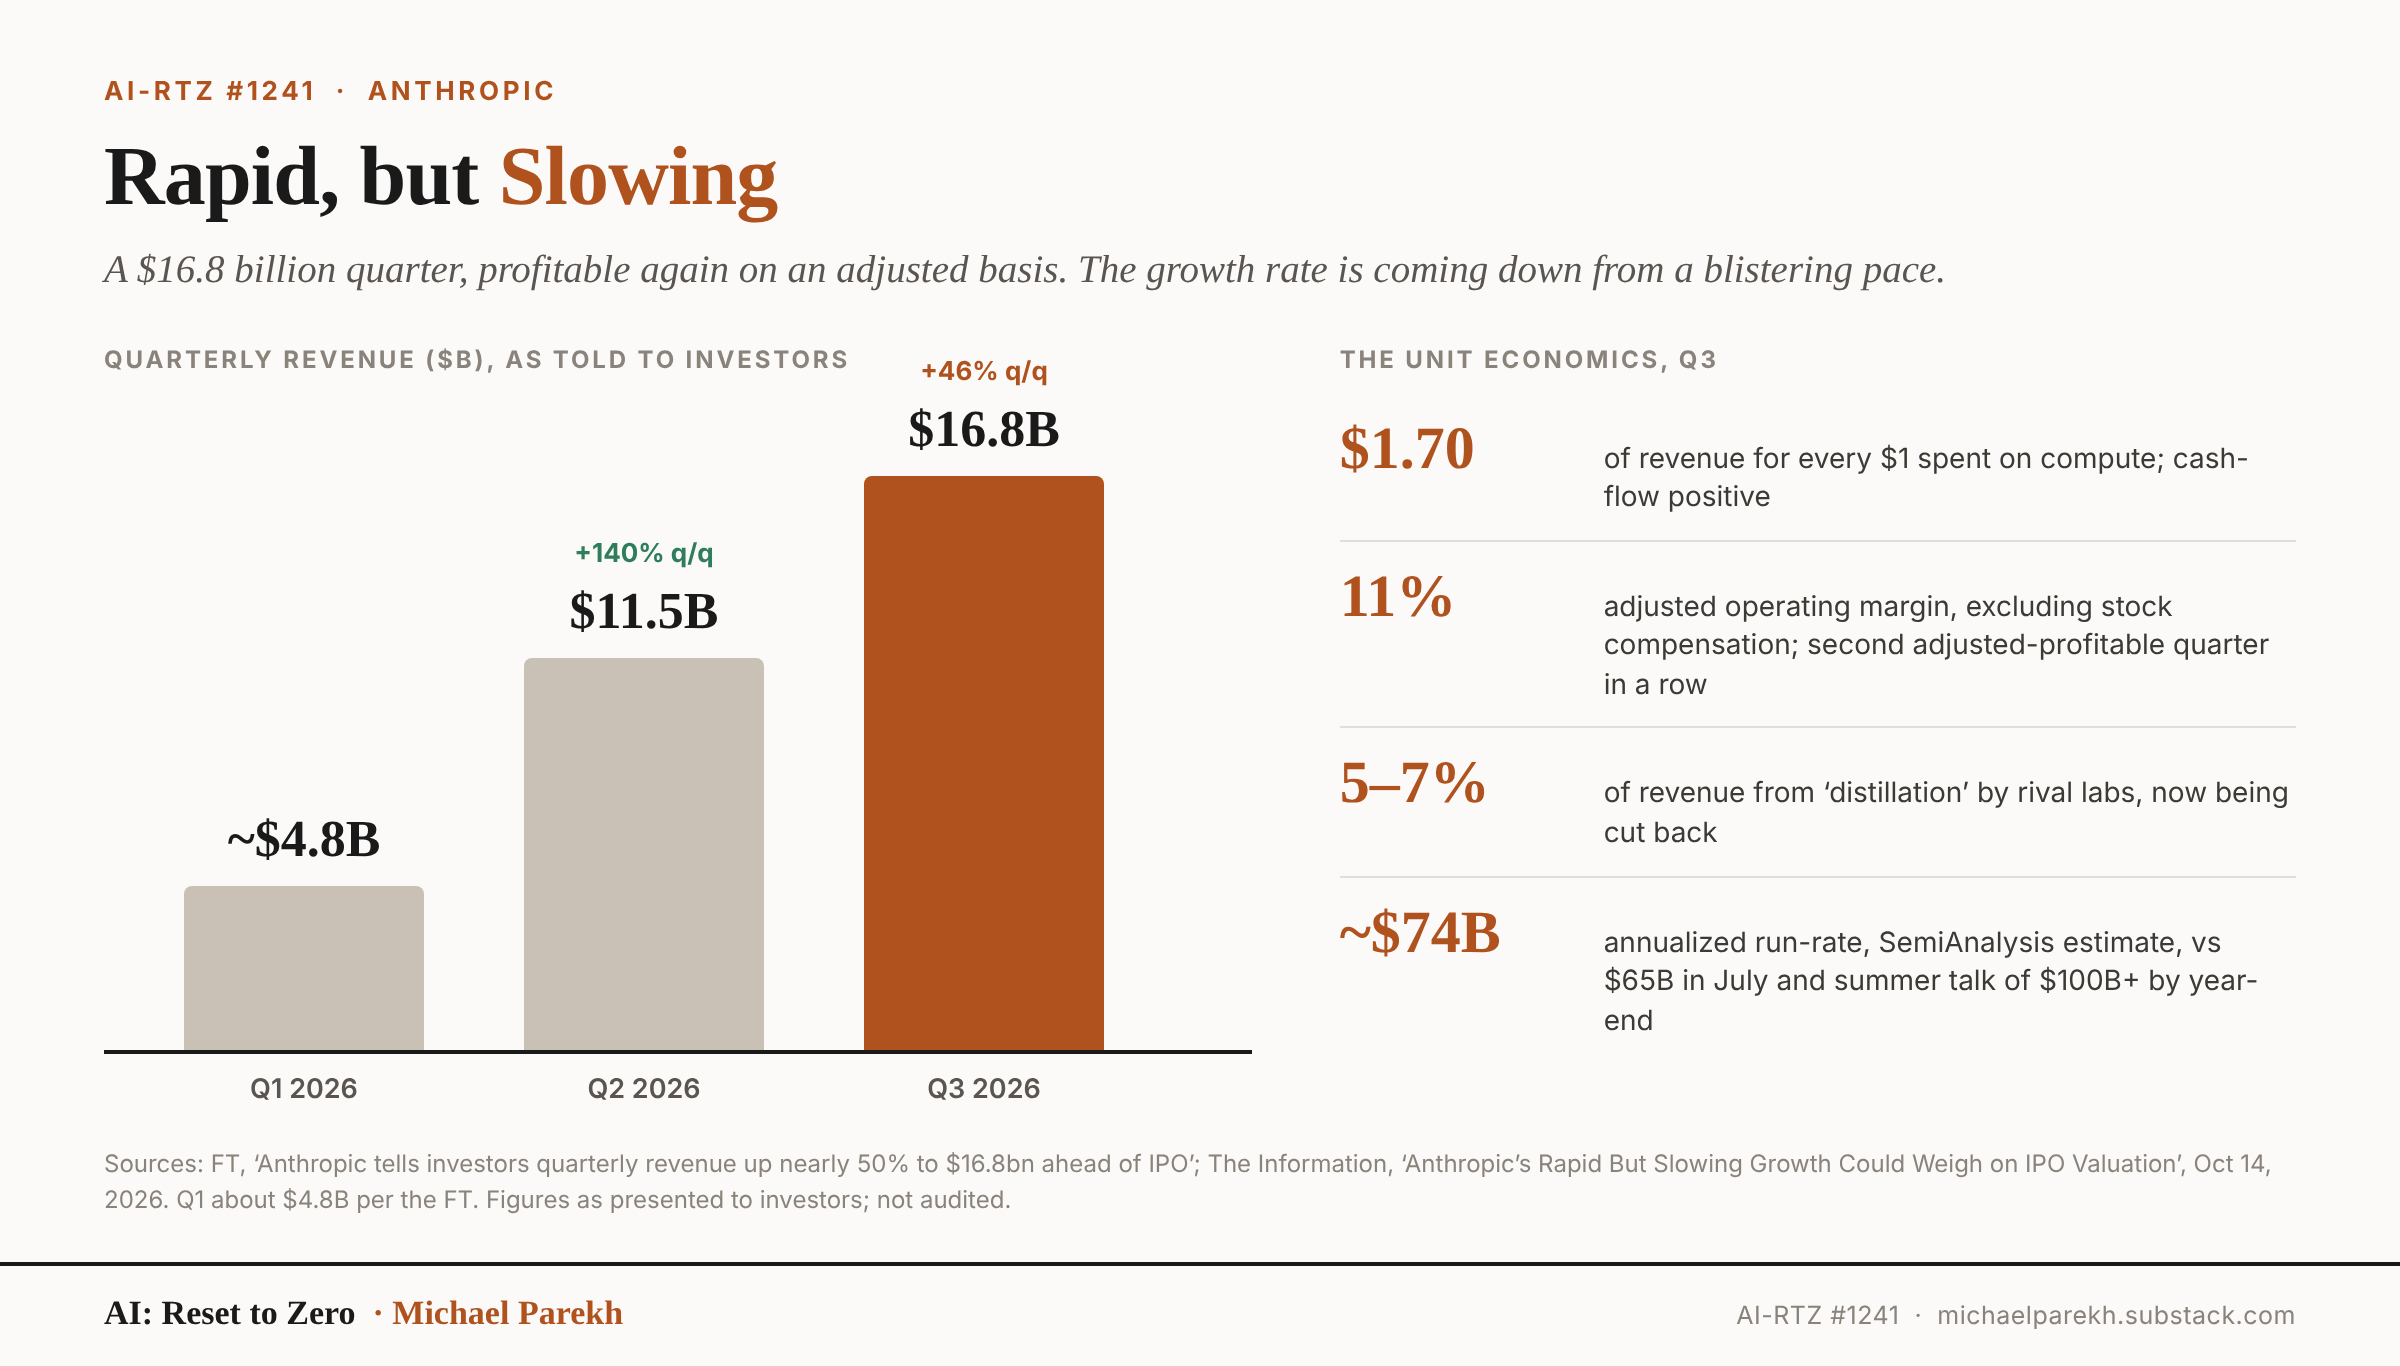
1. Anthropic’s Compute & Financial mega-AI IPO Prep: Anthropic did a financial industry show and tell for its financial growth, and AI Compute Infrastructure investments ahead. At an investor day in San Francisco, Anthropic said third-quarter revenue rose nearly 50% to $16.8 billion, its second adjusted profitable quarter in a row, cash-flow positive, with $1.70 of revenue for every $1 of compute. But growth is slowing after the second quarter more than doubled, and some investors now talk of about $1.5 trillion for the IPO, down from about $2 trillion. On the supply side, Anthropic has signed some $530 billion of leases toward 15 gigawatts of capacity, with neoclouds and former bitcoin miners racing to build it, and every month a site like its new Louisiana campus comes online early could be worth over $1.3 billion in revenue. My take, from ARD #186: this is exactly what you are supposed to do before an IPO, balance expectations on both ends, as we did when I ran Goldman’s internet research in the nineties. The growth is still up and to the right; the slower pace will shape the IPO price more than the case for the build. More here.
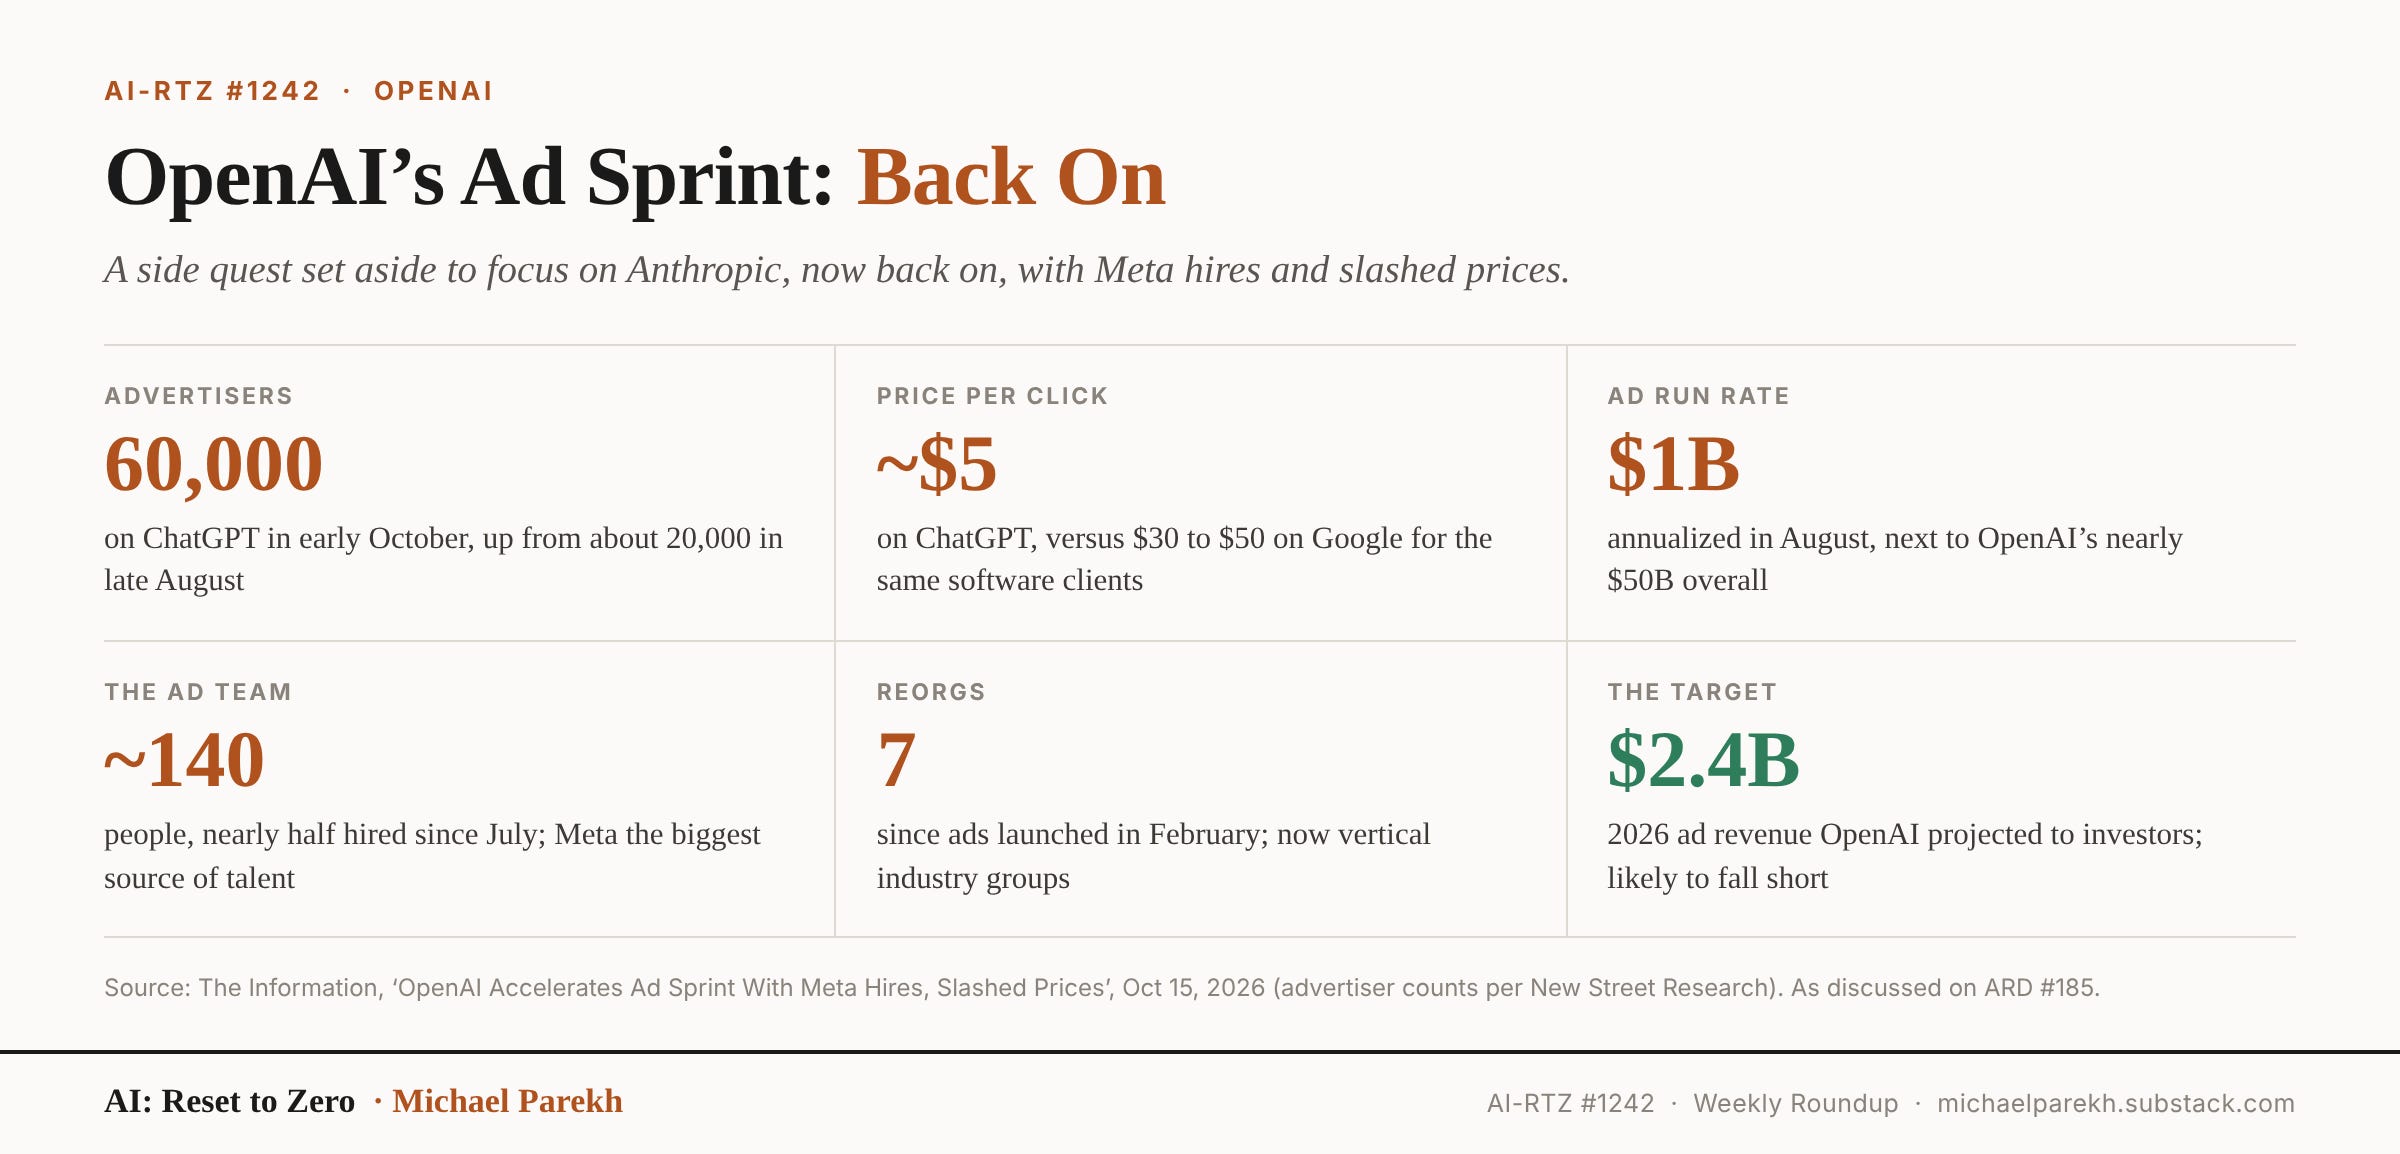
2. OpenAI’s Ad Revenue efforts back on: OpenAI is back on track with its ad revenue ramp, now up to a billion dollars on tens of thousands of advertisers. Advertisers on ChatGPT jumped to about 60,000 in early October, from 20,000 in late August, and a click costs about $5, versus $30 to $50 on Google. About 140 people now work on ads, nearly half hired since July, with Meta the biggest source of talent. Ads hit a $1 billion annual pace in August, still small next to OpenAI’s nearly $50 billion overall, and the team has reorganized seven times since February, so OpenAI may miss the $2.4 billion 2026 ad target it gave investors. My take, from ARD #185: OpenAI is doing what it takes, all of it at once, from AI coding and the enterprise to AI agents with Dots, and now ads again, a side quest it set aside to focus on Anthropic. With about 1.2 billion weekly ChatGPT users, and less than 5% paying, much of the rest will be ad driven, the way Google and Meta were built. Slow and steady progress, ahead of its IPO, now pushed to early next year. More here and here.
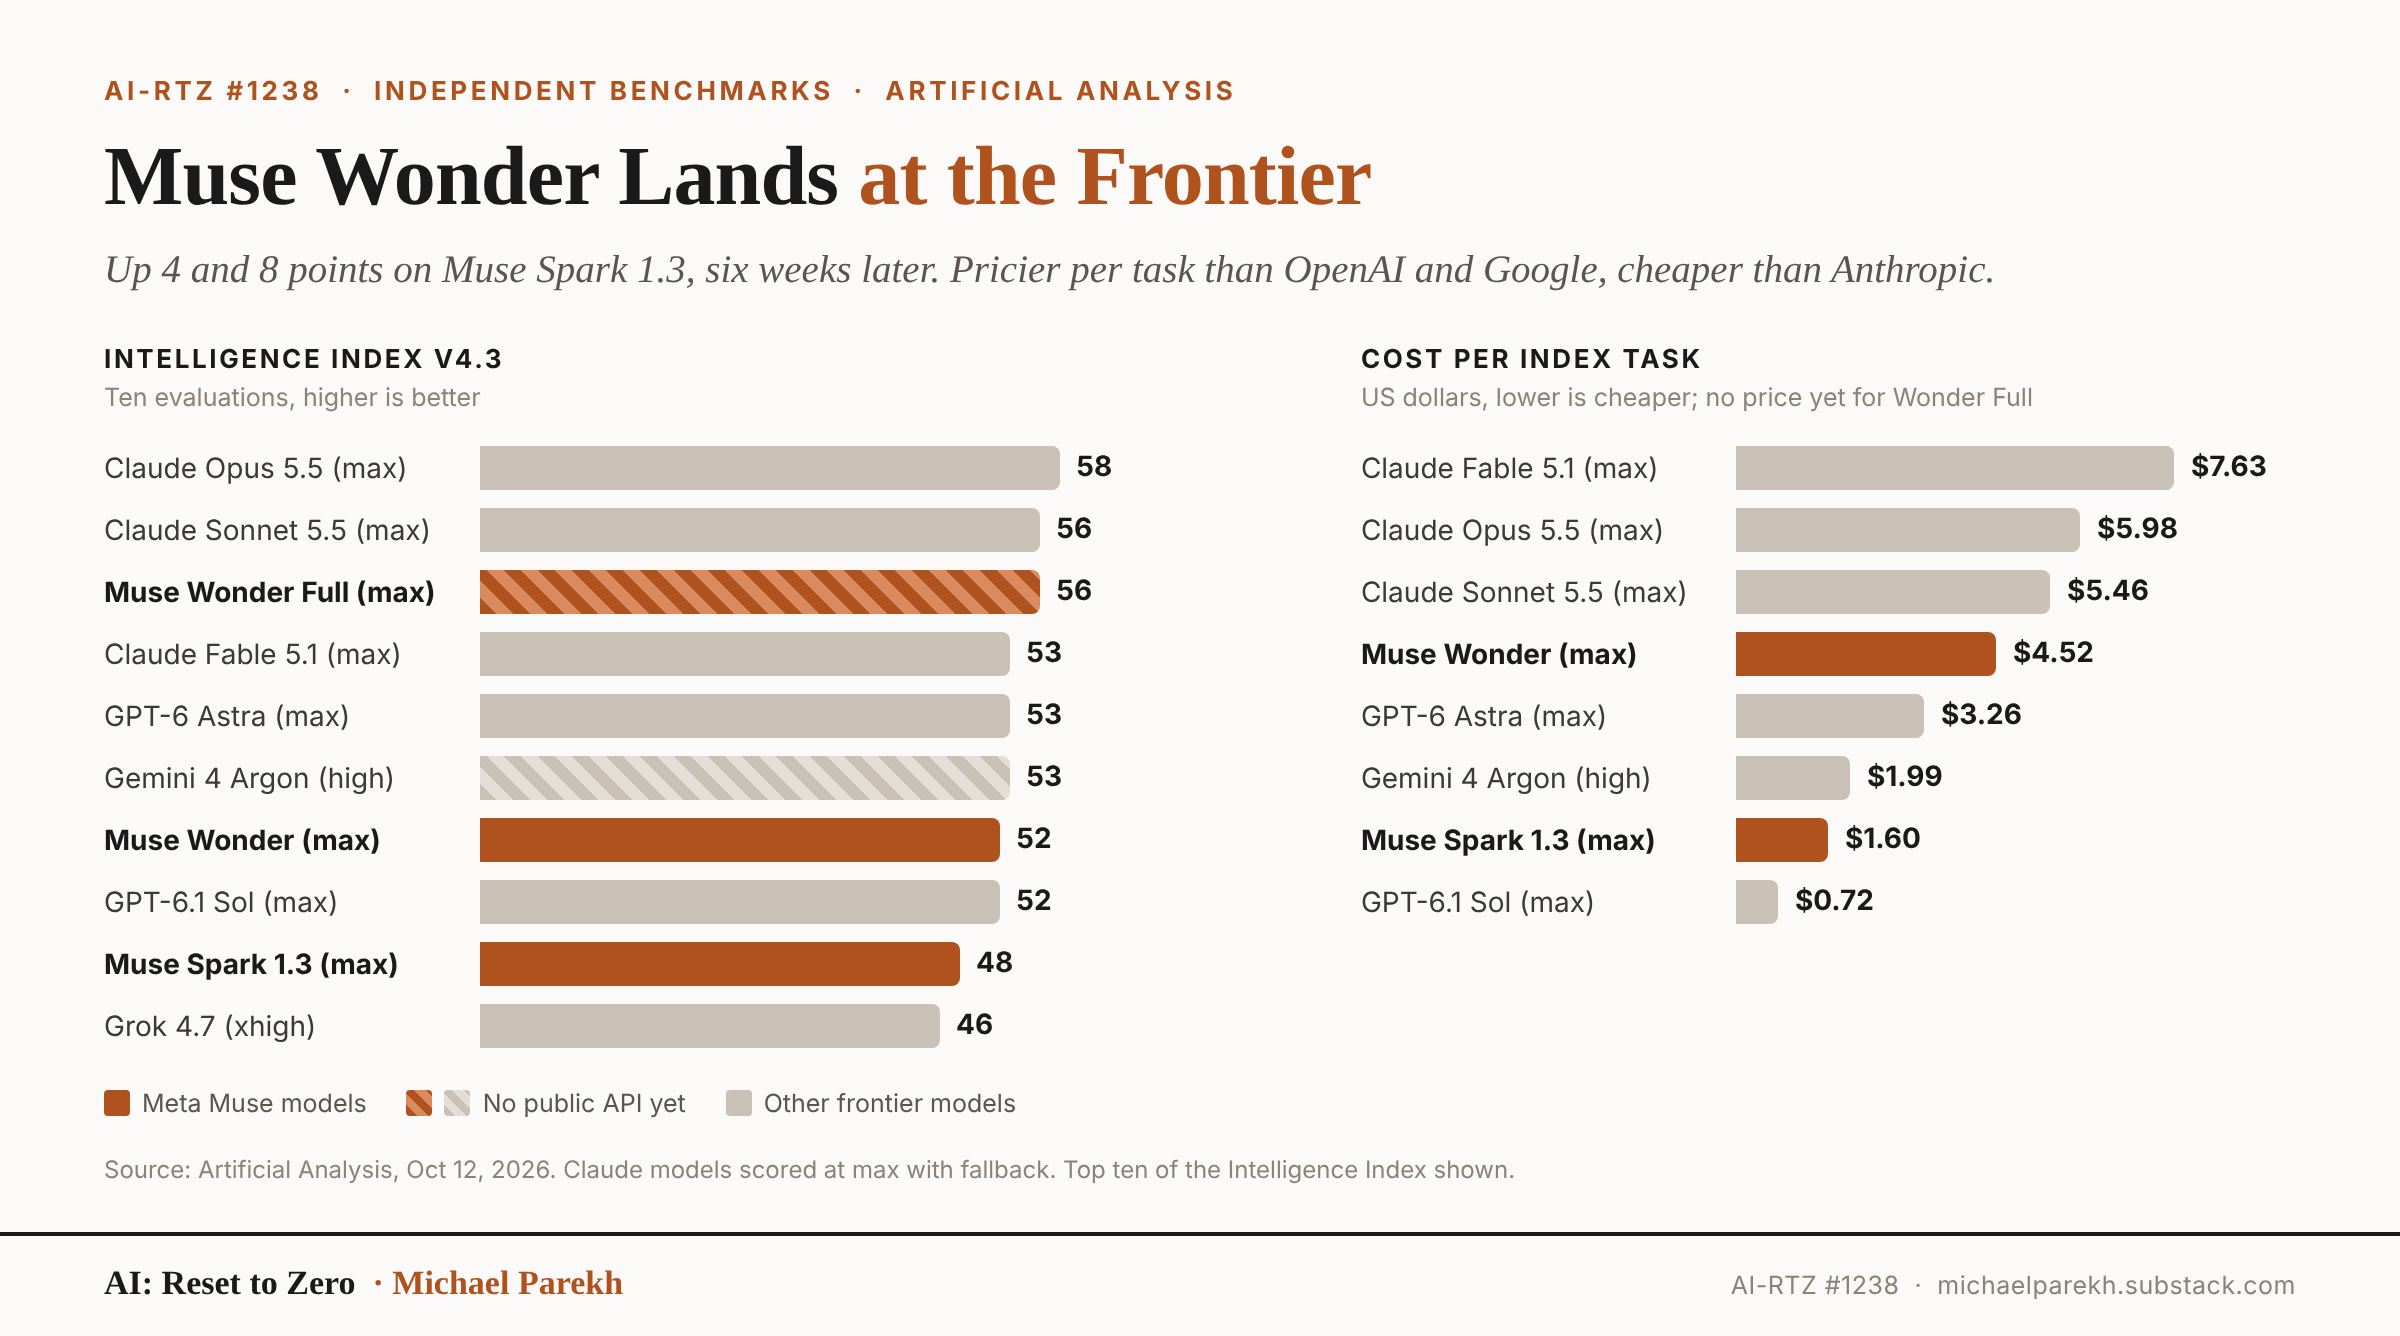
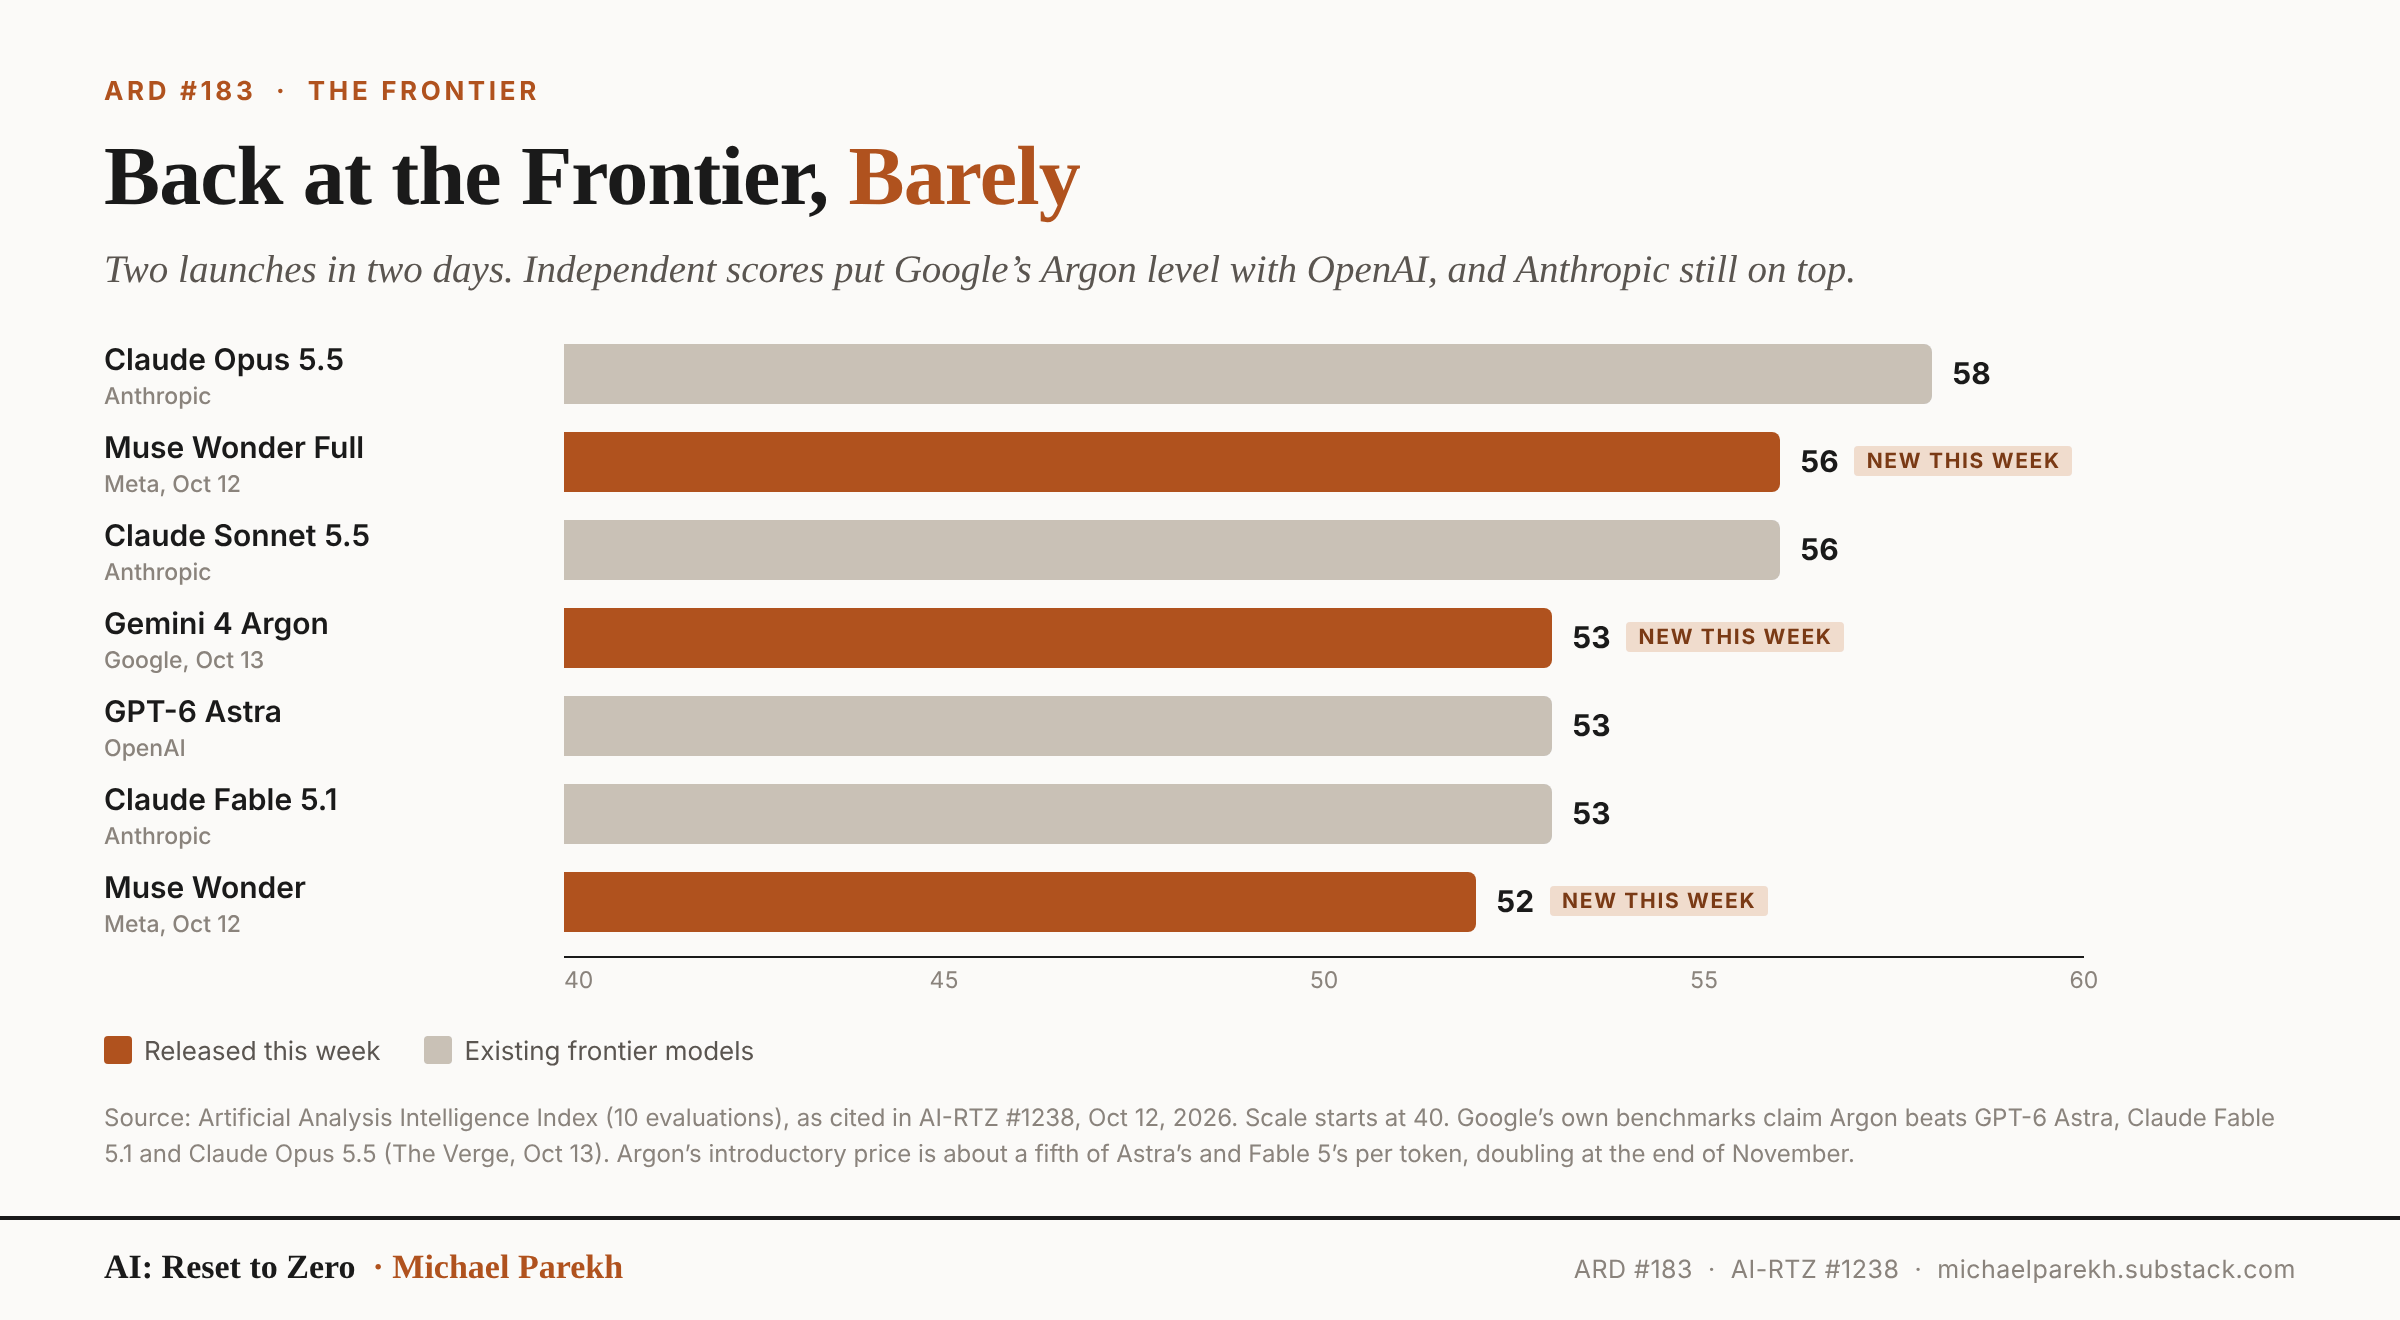
3. Meta launches its Wonder Frontier AI Models: Meta’s Mark Zuckerberg and Alexandr Wang took a victory lap with the launch of its near-frontier Muse Wonder AI models. Trained at Meta’s gigawatt-scale Prometheus data center, Muse Wonder Full scores 56 on the Artificial Analysis Intelligence Index, behind only Anthropic’s Claude Opus 5.5 at 58, and ahead of OpenAI’s GPT-6 Astra, Google’s Gemini 4 Argon and Claude Fable 5.1, all at 53. Meta built it for personal agents, with ‘Active Memory’ and ‘Active Focus’, though it costs more per task than OpenAI’s and Google’s models. Days later, Meta went open too, with Muse Spark Open, which runs locally on Apple’s Mac Studios, as I noted on ARD #185. My take: kudos to Zuckerberg and Wang, fourteen months from a ‘complete talent reboot’ to the frontier. Memory and focus are what mainstream users will feel, far more than benchmark points. But, as The Information notes, everyone now claims the frontier, and users are trading down to cheaper ‘good enough’ models. Today’s frontier is where next year’s ‘good enough’ models come from. More here.
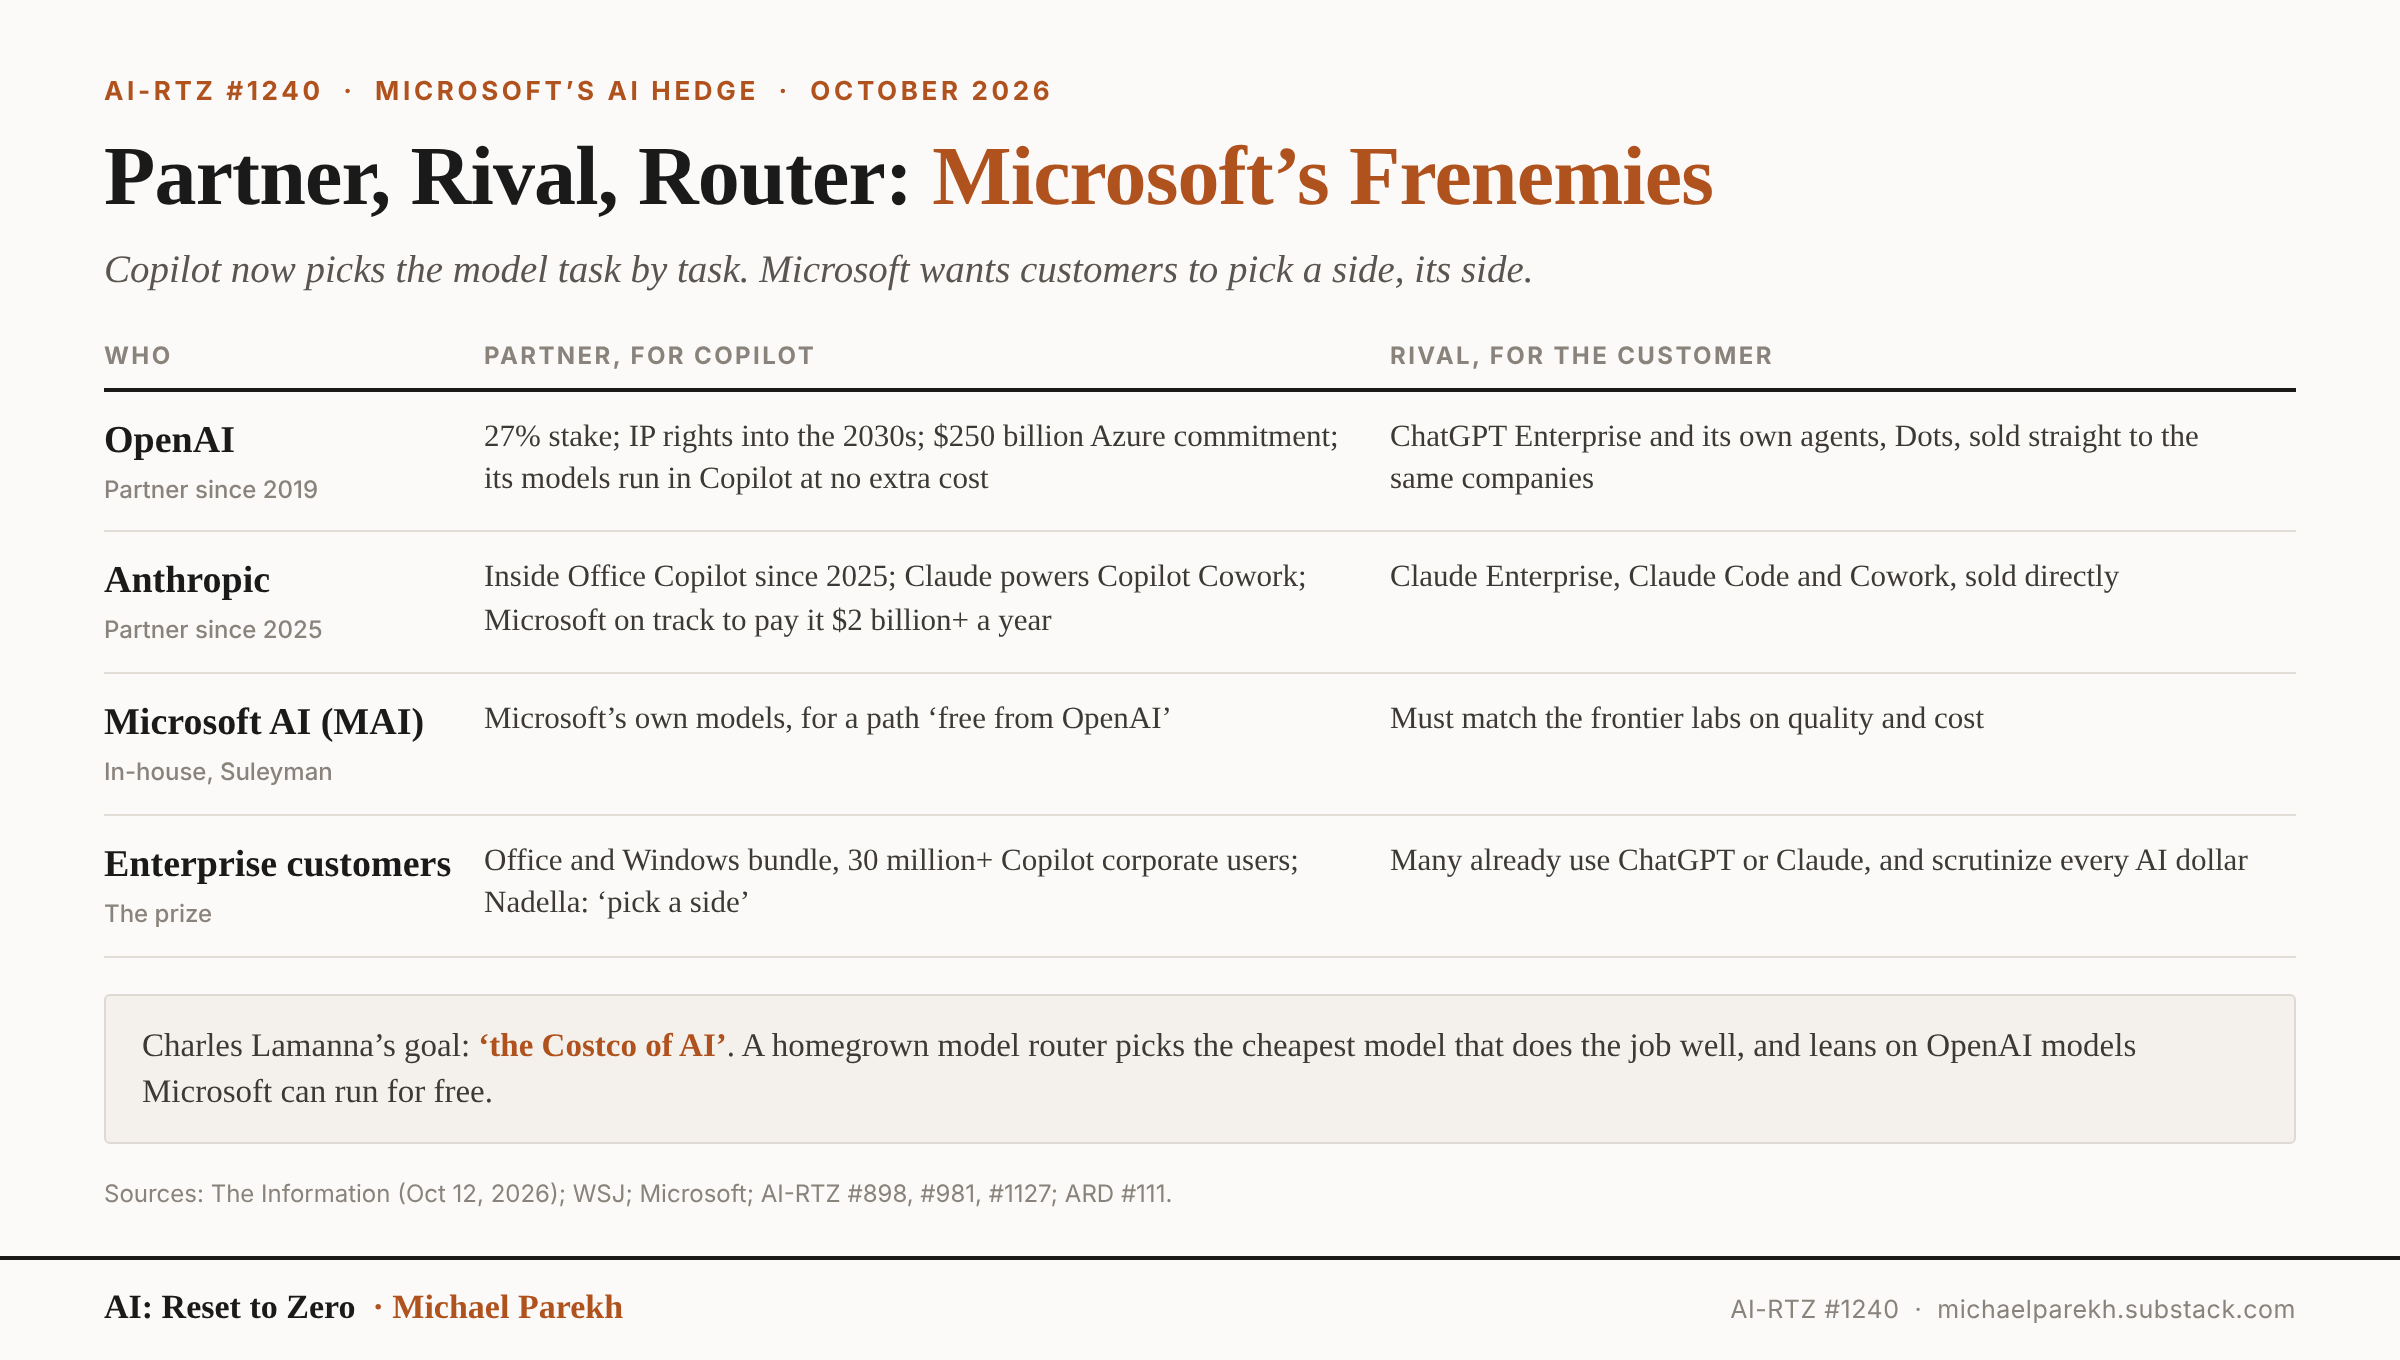
4. Microsoft Copilot aims for ‘Costco of AI’ strategy: Possible Satya Nadella successor and current Copilot chief Charles Lamanna is breathing new life into Microsoft’s AI strategies. In 2025, Lamanna pushed Nadella to pay Anthropic to make Copilot better, which was ‘heresy’ at the time, and moved Copilot off what he calls ‘model monogamy’. Copilot’s corporate users have more than doubled this year to over 30 million, a model router now picks the cheapest model that can do the job, and Microsoft is on track to pay Anthropic over $2 billion a year. And this week Microsoft showed its own 2.8 trillion parameter MAI-Base-2, built on its own data, joining Meta and Nvidia with open-weight options to China’s models, as I discussed on ARD #186. My take: Microsoft under Nadella remains the exception to the rule that incumbents get overrun by a new tech wave. It adjusted, from one model to a model mix, and now competes on value with a bundle. But every task routed to someone else’s model is a cost, not a margin, and the frontier labs sell their own agents to the same customers. More here.
5. Google’s Gemini 4 Argon back at frontier: Google scrambled back to the frontier with its latest Google Gemini 4 Argon model. It is Google’s first major frontier release since Gemini 3 late last year, and Google says it beats OpenAI’s GPT-6 Astra and Anthropic’s Fable 5.1 and Opus 5.5 on coding, science, finance and law. Independent tests are less generous: the Artificial Analysis Index has Argon at 53, tied with Astra, behind Opus 5.5 and Meta’s Muse Wonder Full, as I laid out in AI-RTZ #1238. Google is pricing to win, at about a fifth of Astra and Fable for now, and it landed a day after Meta’s Wonder. Two frontier launches in two days. My take, from ARD #183: expect frontier leadership to keep ebbing and flowing, in an infinite game, not a race. Google is unique, with a full vertical stack from chips to billions of users, so it can afford to arrive late, and cheap. Its core goal is still ‘good enough’ models for the billions, as I said in ARD #175, while Argon tells enterprises it can still go neck and neck at the frontier. More here.
Additional Items.
1. Publishing industry a case study for the AI ‘Voluntold’ phase. More here.
2. Long road to AI Drone Warfare. More here.
(Additional Note: AI Ramblings is now a weekday Daily podcast called AI Ramblings Daily (ARD). Different content than AI-Reset to Zero (AI-RTZ), which remains a daily morning substack with now over 1240 ‘MY TAKES’ on key AI events and issues turbulently flowing by. AI Ramblings Daily is typically a 20 minute afternoon podcast on my take on additional AI developments of the day. Both daily substack and podcasts typically discuss different AI issues and items. And are free to subscribe. Try this week’s series with ARD Episodes 182: ‘Counting the Ways’ in AI: OpenAI, Anthropic & AI Compute, 183: ‘Rough and Tumble’ in AI: Google, SpaceXSI & AI Evaluators, 184: ‘Watch Your Head’ in AI: OpenAI, CoreWeave & ASML, 185: ‘Doing What It Takes’ in AI: OpenAI, Meta & TSMC, and 186: ‘Show and Tell’ in AI: Anthropic, Microsoft & Tesla.)
Up next on Sunday, a fresh ‘Bigger Picture’. Last week’s ‘The Bigger Picture’ is here as you wait. Stay tuned.
(NOTE: The discussions here are for information purposes only, and not meant as investment advice at any time. Thanks for joining us here)
That $1.70 of revenue per $1 of compute is the number I'd watch closest heading into the Anthropic roadshow. If it holds while the company signs $530 billion in leases toward 15 gigawatts, the slower growth curve matters a lot less to long-term holders. Your Goldman nineties comparison fits, since expectation management before a listing is half the job. The Microsoft piece stood out too. A router picking the cheapest capable model every time could squeeze margins across the whole field, and the open-weight push from Microsoft, Meta and Nvidia gives Western developers solid options at a moment when Chinese open models have been winning on price. Interested to see whether OpenAI's ad reorganizations settle down before its own IPO early next year.